Main image
Click to view image in fullscreen
![]()
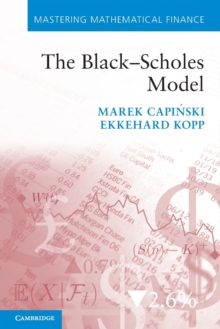
Black-Scholes Model
The authors focus on the key mathematical model used by finance practitioners, the Black-Scholes model, to explore the basic methodology of option pricing with a variety of derivative securities. Students, practitioners and researchers will benefit from the rigorous, but unfussy, approach to technical issues.
320,00 DH
Sur commande
| ISBN / EAN | 9780521173001 |
|---|---|
| Auteur | Capinski, Marek (AGH University of Science and Technology, Krakow) |
| Editeur | Cambridge University Press |