Main image
Click to view image in fullscreen
![]()
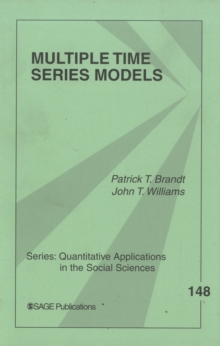
Multiple Time Series Models
Reviews the main competing approaches to modeling multiple time series: simultaneous equations, ARIMA, error correction models, and vector autoregression. This book focuses on vector autoregression (VAR) models as a generalization of the other approaches mentioned. It also reviews arguments for and against using multi-equation time series models.
330,00 DH
Sur commande
Reviews the main competing approaches to modeling multiple time series: simultaneous equations, ARIMA, error correction models, and vector autoregression. This book focuses on vector autoregression (VAR) models as a generalization of the other approaches mentioned. It also reviews arguments for and against using multi-equation time series models.
| ISBN / EAN | 9781412906562 |
|---|---|
| Auteur | Brandt, Patrick T. |
| Editeur | SAGE Publications Inc |